On October 29, Florida's Office of Insurance Regulation said lower home insurance rates reached more than 824,300 Florida homeowners in October, at new policies and renewals. The cuts ranged up to 12.1%. The state also said about 450,000 more decreases are pending for November, December and January. It did not name those companies yet.
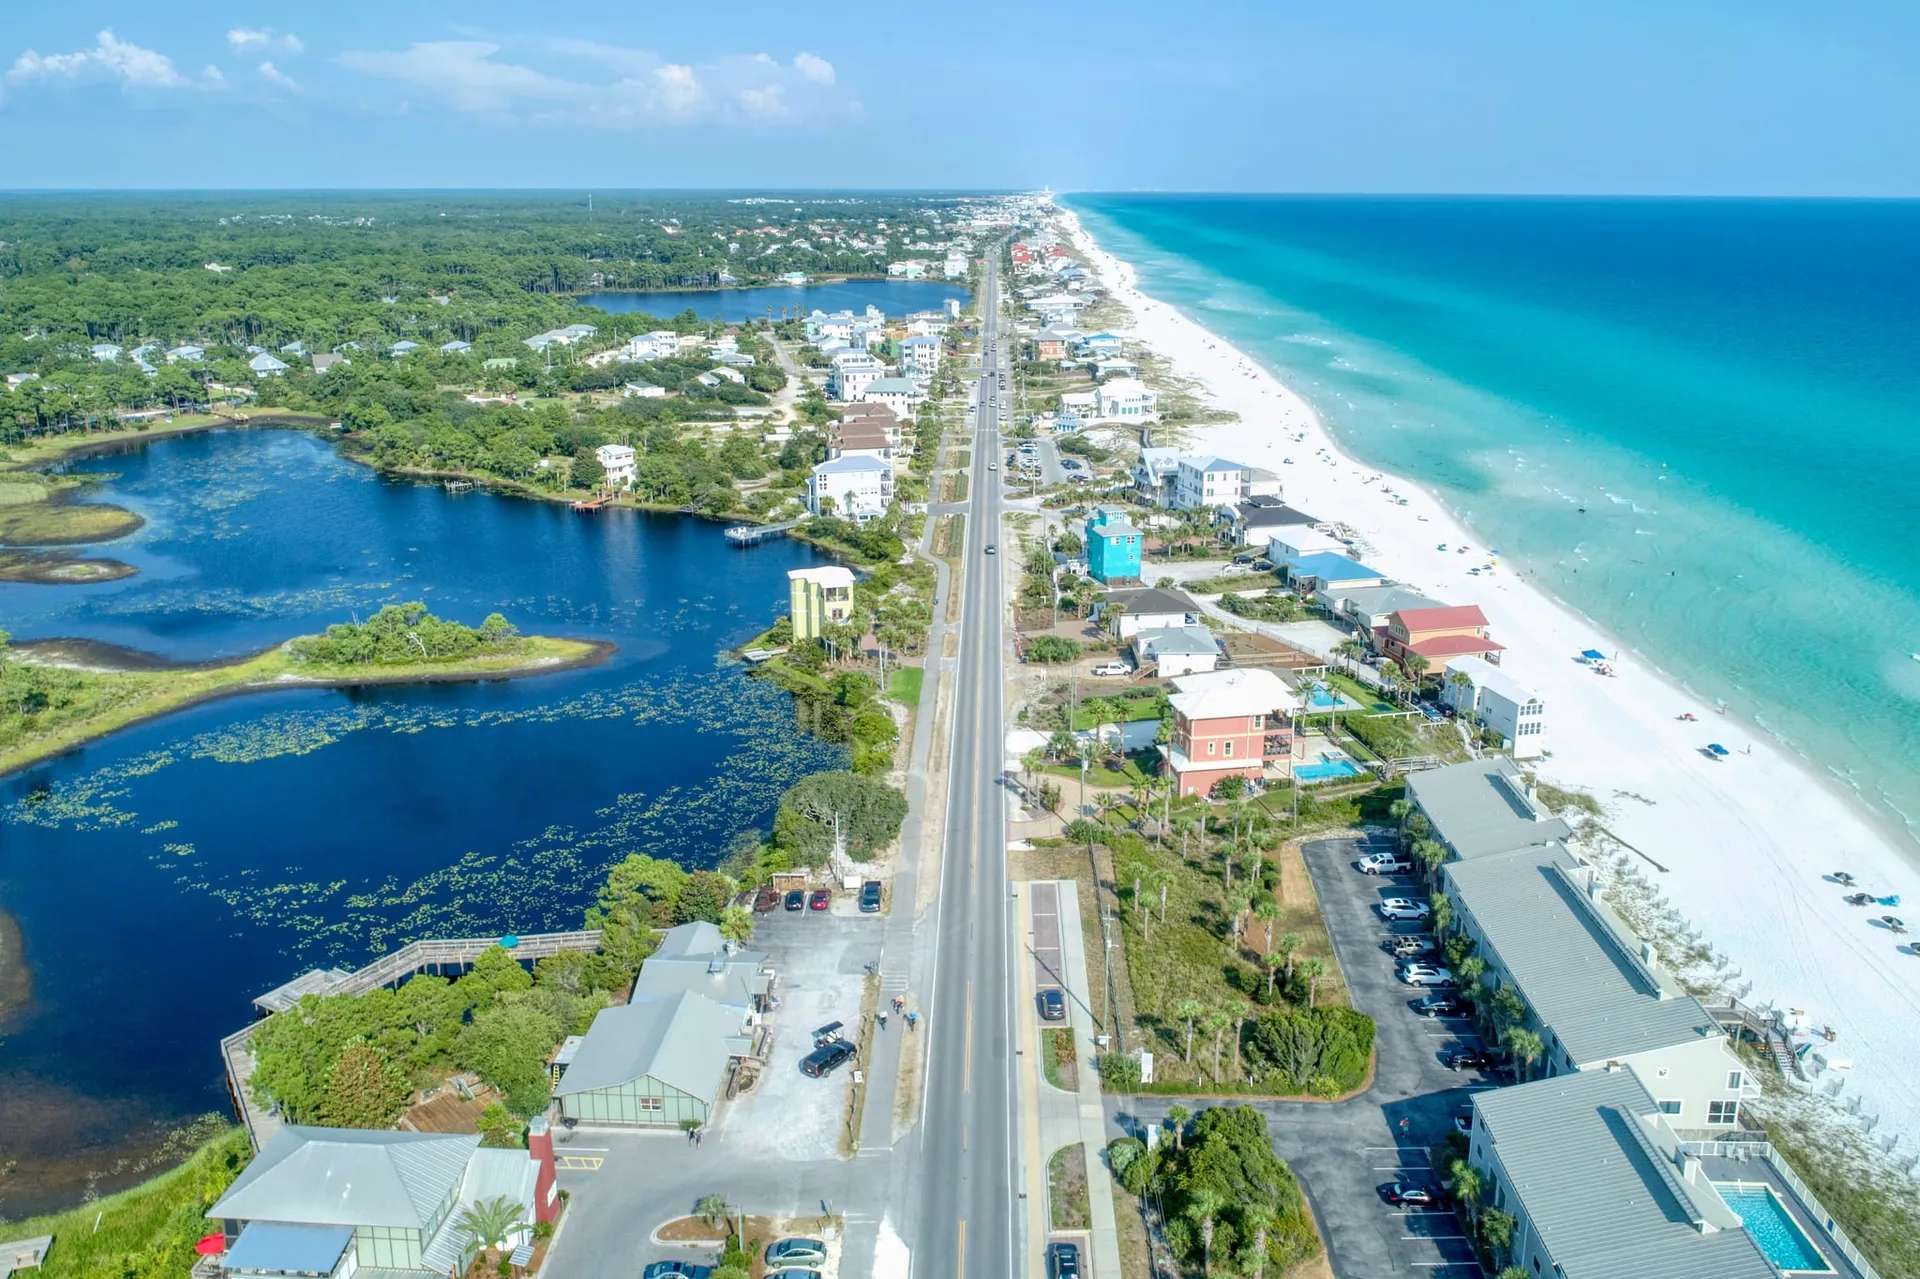
This is a statewide story, but it reaches every home on 30A, from Inlet Beach to Dune Allen. Insurance is now one of the biggest costs of owning here, so even a small change matters. Over the years I've watched insurance grow into one of the first things people ask about when they look at a home on 30A.
Who got a cut in October
Nine rate filings took effect during October. Each one is a company average, so a single policy can move more or less. Here is what the state listed:
- Universal Property & Casualty: about 5% on 512,000 policies, effective October 16
- Kin Insurance: about 3.4% on 99,800 homeowners policies, effective October 8
- Olympus Insurance: about 0.1% on 66,800 policies, effective October 31
- Cypress Property & Casualty: about 12.1% on 64,300 policies, effective October 1
- Mangrove Insurance: about 5.6% on 4,000 homeowners policies, effective October 27
- Condo unit-owner cuts from Castle Key Indemnity (12% and 10.3%), Security First (7.3%) and Manatee Insurance Exchange (3.5%)
The 12.1% figure is the top of the range, and it came from one company. Most of the policies on the list sit with Universal at about 5%. Several of the larger percentages apply only to condo unit-owner policies. If you insure a house, a condo filing does not change your rate, even if your company's name is on the list.
Why your bill may not drop
A rate cut reaches you at your first new policy or renewal on or after its effective date. If you renewed a few days before your company's cut took effect, you renewed at the old rate.
Your bill can also rise while your rate falls. Many policies raise dwelling coverage each year to keep up with building costs, and that raises the premium. A percentage hurricane deductible grows with it. A lapsed wind mitigation report can cost you a discount. Some companies price by roof age, so an older roof can move a home into a new pricing band.
A simple check is to set last year's declarations page next to this year's. Compare the dwelling coverage, the hurricane deductible and the total premium. If coverage stayed the same and your company filed a cut, but your premium did not go down, it is fair to ask your insurance agent why.
The Citizens flood rule on January 1
If your home is insured through Citizens, there is a bigger date ahead. Starting January 1, 2027, any Citizens Property Insurance policy on a home that covers wind will need flood coverage too, for both new policies and renewals. That applies no matter the dwelling's value. Homes inside a special flood hazard area already had this rule.
Some policies don't fall under the new rule: those for condo unit owners, renters' contents, and any policy that leaves out wind. The flood coverage must at least equal the Citizens dwelling value, or the National Flood Insurance Program maximum the home qualifies for.
For Citizens owners outside a flood zone, this means a new premium to plan for. If you are on Citizens, it is worth getting a flood quote before your renewal comes up.
Hurricane Isaias and what comes next
Hurricane Isaias came ashore near Destin on the night of October 9 as a Category 2 storm. By late October, the state's tally stood at close to 55,000 claims, with insured losses near $582 million. The bulk of the claims came from Santa Rosa, Escambia and Okaloosa counties. Those losses land on the same companies that filed this year's cuts. No rate filing tied to Isaias had been made public as of this week.
Governor-elect Byron Donalds has also said he wants to end a 25% charge that the state's hurricane catastrophe fund adds to what insurers pay for its reinsurance. That is only a proposal for now, with no bill written.
What it means for owners and buyers
If you own a home here, look up your company and policy type, then check the effective date against your renewal. If your company is not on the list, matching quotes from two or three others can show you where you stand. An up-to-date wind mitigation inspection often brings one of the bigger discounts.
If you are shopping for a home, ask for an actual insurance quote on that house during your inspection period. On an older home, a four-point and wind mitigation inspection can shape that quote a great deal. Put insurance, property taxes and any HOA dues together into one monthly number before you commit. You can browse homes across the area at livebythebeach.com/properties.
Questions about anything here, or about a home on 30A?
Ask Garett